
Strategic Insights for Deal Flow Decision-Makers
Qualified Small Business Stock (QSBS) remains a powerful incentive, but in today’s more complex, diligence-heavy deal environment, its benefits depend less on initial eligibility and more on whether transaction strategy and execution are aligned early enough to preserve value through closing.
In prior years, much of the discussion around QSBS focused on entity selection and early-stage compliance. For founders and investors, forming a C corporation and holding stock for the requisite period was often viewed as sufficient groundwork for securing favorable tax treatment at exit.
While those fundamentals remain important, today’s deal environment has introduced new complexities, such as transactions that are taking longer to close, liquidity events that are occurring in stages, and buyers that are applying greater scrutiny throughout the diligence process. As a result, QSBS outcomes are increasingly influenced not just by eligibility at formation, but by the structure and sequencing of the deal itself.
Historically, QSBS planning emphasized upfront decisions: capitalization, asset composition, and adherence to the active business requirements. These considerations still form the foundation of eligibility, but they no longer tell the full story.
In the current market, many companies experience multiple inflection points well before a full exit. Growth equity investments, recapitalizations, minority sales, and founder liquidity transactions are now common. Each of these events can affect QSBS treatment in ways that are not always obvious when the transaction is first contemplated.
One notable shift in recent years has been the rise of partial liquidity. Founders and early investors are increasingly monetizing a portion of their holdings prior to a full sale, either through secondary transactions or strategic recapitalizations. While these transactions can provide meaningful personal and financial flexibility, they can also introduce tax consequences that differ from expectations formed at the outset of the investment.
At the same time, buyers are exercising greater control over transaction structure. Asset acquisitions, purchase price allocations, and rollover equity arrangements are often driven by diligence findings and risk assessments. Tax diligence has also become more comprehensive. Buyers are increasingly focused on historical activities, capitalization changes, and prior transactions that could affect tax exposure post-close.
In today’s environment, the most effective QSBS strategies are those that preserve optionality by aligning operational decisions, capital strategy, and documentation well before a transaction is on the horizon, with an awareness of how future transactions may unfold.
Four Deal Decisions that Shape QSBS Outcomes
- Deal structure choices: Whether a transaction is structured as a stock or asset sale and how rollovers and recap mechanics are handled can preserve or eliminate QSBS benefits.
- Timing and sequencing of liquidity events: Partial exits, secondaries, or redemptions can unintentionally disrupt holding periods or available exclusions.
- Whether tax diligence drives the deal or the deal drives diligence: Historical activities, capitalization changes, and prior transactions are now scrutinized more deeply and can directly affect value.
- Early alignment between tax strategy and transaction strategy: Waiting until LOI or diligence often removes flexibility and turns a potential tax advantage into a missed opportunity.
The Bottom Line
QSBS remains a powerful incentive for founders and investors, but it is no longer automatic. As deal structures become more complex and diligence more exacting, tax outcomes are increasingly shaped by execution rather than intent.
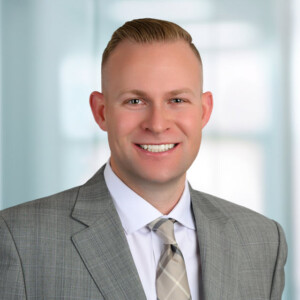
Joel Racker, Audit Partner, Richey May
Joel is an audit partner based in Richey May’s Salt Lake City office. Joel’s expertise includes audits of large SEC public companies, private companies and companies considering going public in the Software/SaaS, Life Science, and consumer products space.